
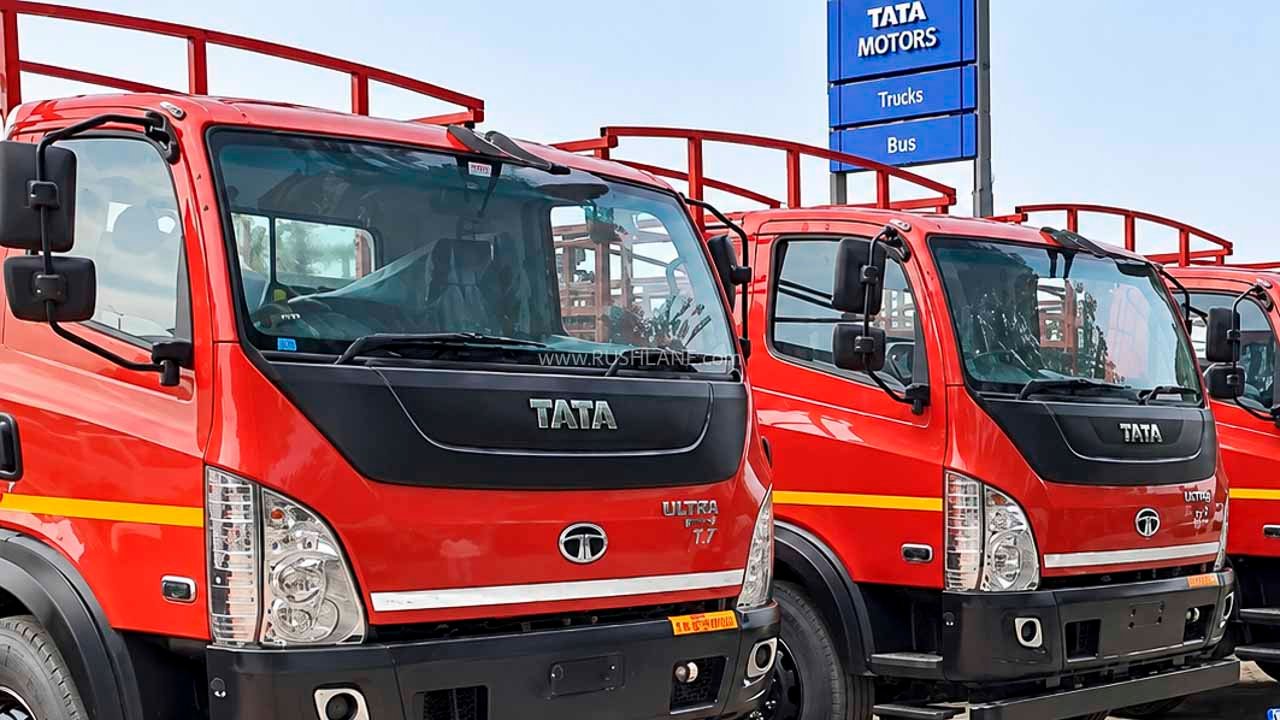
The commercial vehicle (CV) retail segment recorded a strong performance in October 2026, achieving its highest-ever October sales
The commercial vehicle (CV) retail segment registered its highest-ever October last month. Total retail sales stood at 1,15,140 units, registering a 2.29% year-on-year (YoY) growth over the 1,12,561 units sold in October 2025. On a month-on-month (MoM) basis, sales increased by 11.19% compared to 1,03,557 units recorded in September 2026. Of the eight OEMs covered in the sales data, only Mahindra and Maruti Suzuki reported a YoY decline.
A category-wise analysis reveals contrasting trends across the CV segment. Light Commercial Vehicle (LCV) sales declined by 9.57% YoY to 69,148 units. In contrast, Medium Commercial Vehicle (MCV) sales increased by 21.16% to 9,042 units, while Heavy Commercial Vehicle (HCV) sales registered a robust 28.95% growth. The ‘Others’ category also nearly doubled its volumes, recording 71 units, up 97.22% from 36 units in October 2025.
The segment also maintained strong momentum on a year-to-date (YTD) basis. CV retail sales during April–October 2026 stood at 7,02,405 units, marking an 18.17% increase over the 5,94,384 units recorded during the corresponding period last year.
CV Retail Sales Oct 2026 – Diesel Vehicles Continue to Dominate
Diesel-powered vehicles continued to dominate the commercial vehicle market, accounting for an overwhelming 81.40% share of total retail sales in October 2026. CNG/LPG vehicles followed with an 11.31% share, while petrol/ethanol models accounted for 2.97%. Electric vehicles (EVs) held a 4.29% share, whereas hybrids contributed a marginal 0.03%.
CV retail sales recorded growth in urban markets, increasing 6.51% YoY and 15.47% MoM. Rural markets, meanwhile, registered a 6.51% MoM improvement but witnessed a 2.29% decline on a YoY basis, indicating relatively subdued demand in these regions.
CV Retail Sales Oct 2026
Commercial vehicle retail sales list saw Tata Motors leading with 39,914 units sold in the past month to command a 34.67% market share. At no. 2, Mahindra sales declined to 31,500 units, down from 38,602 unit sales of Oct 2025. The company reported a dip in market share to 27.36%.
Ashok Leyland sales improved to 20,774 units from 17,797 units on a YoY basis taking up market share to 18.04%. VECV secured fourth position with 9,603 units sold last month, a volume growth of 1,668 units over 7,935 units sold in Oct 2025. Market share also improved to 8.34% from 7.05% YoY.
CV retail sales of Maruti Suzuki declined to 5,041 units in the past month from 6,147 units sold in the same month last year. This also brought down market share to 4.38% from 5.46%. Force Motor sales went up to 2,363 units in Oct 2026 while Daimler recorded retail sales at 2,205 units.
SML Mahindra also posted stronger growth at 1,054 units, up from 1,027 units sold in the same month of last year. There were others on this list that added 2,686 units to total sales, a significant growth over 1,189 units sold in Oct 2025.
Federation of Automobile Dealers Associations (FADA) indicates an optimistic outlook for the CV market outlook for November 2026–January 2027 period. Dealers anticipate healthy demand over the next three months, supported by continued activity across infrastructure development, mining and e-commerce.