
Victoris, Seltos and Sierra drove much of the segment’s growth, while Maruti Suzuki led manufacturer-wise sales in September and Q3 2026
After taking a look at the sub 4m SUV sales, let us now take a look at the 4.2m–4.5m SUV segment, which continues to expand, with newer entrants challenging established names and bringing additional volumes. September 2026 sales reached 82,179 units, growing 40.23% over 58,602 units a year earlier. Volumes also increased 3.12% compared with August’s 79,691 units.
4.2m to 4.5m SUV Sales Sep 2026
Hyundai Creta recorded 17,657 units in September, accounting for 21.49% of the segment. Sales declined 6.38% from 18,861 units a year earlier but improved 8.40% over August. Maruti Victoris ranked second with 13,111 units, growing 207.70% against a relatively low year-ago base of 4,261 units.
| No | SUV Sales (4.2m – 4.5m) | Sep-26 | Sep-25 |
|---|---|---|---|
| 1 | Hyundai Creta / EV | 17,657 | 18,861 |
| 2 | Maruti Victoris | 13,111 | 4,261 |
| 3 | Kia Seltos | 12,593 | 5,816 |
| 4 | Maruti Grand Vitara | 8,513 | 5,698 |
| 5 | Tata Sierra / EV | 7,205 | 0 |
| 6 | Toyota HyRyder | 7,115 | 7,608 |
| 7 | Mahindra Thar ROXX | 5,625 | 7,973 |
| 8 | Tata Curvv / EV | 2,610 | 1,566 |
| 9 | Mahindra BE 6 | 1,517 | 1,701 |
| 10 | Maruti eVitara | 1,342 | 0 |
| 11 | Skoda Kushaq | 1,152 | 769 |
| 12 | Volkswagen Taigun | 994 | 1,144 |
| 13 | Honda Elevate | 599 | 2,199 |
| 14 | Renault Duster | 465 | 0 |
| 15 | Nissan Tekton | 409 | 0 |
| 16 | VinFast VF6 | 323 | 218 |
| 17 | MG Astor | 284 | 90 |
| 18 | MG ZS EV | 280 | 250 |
| 19 | Toyota Ebella | 166 | 0 |
| 20 | Force Gurkha 5D | 108 | 30 |
| 21 | Citroen C3 Aircross | 70 | 59 |
| 22 | Citroen Basalt | 28 | 210 |
| 23 | Mahindra XUV400 | 13 | 149 |
| – | Total | 82,179 | 58,602 |
Kia Seltos followed with 12,593 units, more than doubling its September 2025 tally of 5,816 units. Growth stood at 116.52% year-on-year and 7.49% month-on-month. Together, the top three accounted for approximately 53% of the segment’s September volumes. Grand Vitara finished fourth with 8,513 units, registering 49.40% annual growth and a 9.03% sequential increase.
Sierra Enters Top Five
Tata Sierra recorded 7,205 units, growing 28.16% over August’s 5,622 units. Its addition of 1,583 units was the largest sequential volume gain in the segment. Sierra finished just 90 units ahead of Toyota Hyryder, which recorded 7,115 units, down 6.48% year-on-year and 13.59% month-on-month.
Mahindra Thar ROXX followed with 5,625 units, declining 29.45% annually and 3.30% sequentially. Tata Curvv, including EV sales, registered 2,610 units, growing 66.67% over September 2025 and 37.08% over August. Mahindra BE 6 contributed 1,517 units, down 10.82% year-on-year, while Maruti e Vitara completed the top 10 with 1,342 units. Both recorded sequential declines.
Kushaq Grows, Elevate Falls Below 600 Units
Skoda Kushaq sold 1,152 units, growing 49.80% year-on-year and 9.92% month-on-month. Volkswagen Taigun recorded 994 units, down 13.11% annually but up 5.97% sequentially. Honda Elevate declined sharply to 599 units from 2,199 units a year earlier. Renault Duster followed with 465 units, Nissan Tekton with 409 units and VinFast VF6 with 323 units. Duster hybrid has just been launched, which could sales in coming months.
MG Astor recorded 284 units, ahead of ZS EV at 280 units, while Toyota Ebella contributed 166 units. Force Gurkha 5D, Citroen C3 Aircross, Citroen Basalt and Mahindra XUV400 rounded off the list with 108, 70, 28 and 13 units, respectively.
Q3 2026 Sales Grow 52.45%
For July–September, segment sales reached 2,43,862 units, up 52.45% from 1,59,967 units in Q3 2025. Creta retained the lead with 52,033 units, although growth was marginal at 0.68%. Victoris ranked second with 37,423 units, followed closely by Seltos at 36,850 units. Their respective increases of 33,162 and 20,337 units made them the largest contributors to quarterly growth.
Grand Vitara recorded 24,448 units, up 37.24%, while Hyryder declined 11.70% to 22,536 units. Sierra added 19,154 units, followed by Thar ROXX at 17,194 units, down 12.46%. Together, the gains from Victoris and Seltos and the addition of Sierra accounted for approximately 87% of the segment’s net quarterly increase.
Curvv recorded 6,211 units, growing 17.77%, while e Vitara contributed 4,603 units. Elevate, BE 6 and Taigun declined to 3,874, 3,754 and 3,157 units, respectively. Kushaq grew 23.34% to 3,033 units, followed by Tekton at 2,570 units.
Maruti Suzuki Leads OEM Rankings
Maruti Suzuki recorded combined segment sales of 22,966 units in September, growing 130.61% year-on-year and securing a 27.95% share. Hyundai followed with 17,657 units, while Kia ranked third with 12,593 units. Tata reached 9,815 units, with Sierra helping lift volumes substantially over the year-ago Curvv tally. Toyota recorded 7,281 units, declining 4.30%, while Mahindra fell 27.16% to 7,155 units.
The quarterly OEM rankings followed the same order. Maruti led with 66,474 units, ahead of Hyundai’s 52,033, Kia’s 36,850 and Tata’s 25,365 units. Maruti alone contributed nearly 53% of the segment’s net quarterly increase, underlining the impact of its broader lineup.
More Competition On The Way
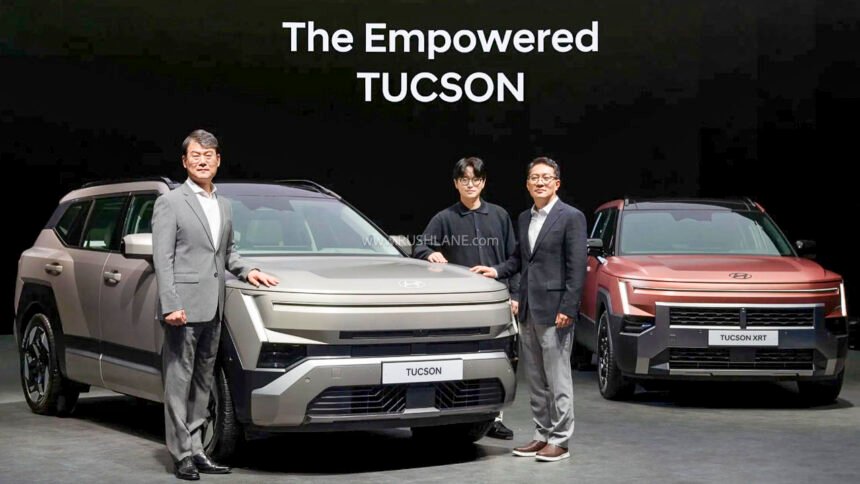
The 4.2m–4.5m SUV space has grown from a relatively small field into one of India’s most fiercely contested segments. Much of today’s lineup arrived after the COVID-19 lockdowns, giving buyers a wider choice of petrol, diesel, hybrid and electric powertrains. Among the familiar pre-pandemic names, Creta and Seltos continued uninterrupted, while S-Cross, Terrano and Captur exited. Duster has since returned, and Nissan is competing again with Tekton.
Hyundai Bayon’s October 26 launch will add another contender. With Creta still leading the model rankings, Bayon could provide the additional volumes Hyundai needs to challenge Maruti Suzuki for the segment’s OEM sales crown.